What is the Defense Cyber Security Market and its scope?
Our analysis indicates the Defense Cyber Security Market encompasses specialized hardware, software, and services designed to safeguard military networks, intelligence agencies, and government defense infrastructure against sophisticated cyber warfare threats and nation-state actors.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Rising state-sponsored cyber espionage acts as a primary market driver, while severe legacy system integration challenges and strict compliance mandates across agencies like the Department of Defense act as notable restraints, opening pathways for advanced cloud security integration.
Emerging trends and growth patterns in Defense Cyber Security Market
The data suggests a rapid pivot toward Zero Trust architecture and AI-driven automated threat hunting. Industry leaders like Palantir Technologies Inc. and CrowdStrike Holdings Inc. are spearheading these initiatives to counter rapidly mutating ransomware and persistent threats.
How did COVID-19 impact the Defense Cyber Security Market?
The pandemic accelerated remote work requirements for defense contractors, driving an urgent surge in demand for secure communication devices, encryptors, and robust endpoint detection tools from vendors like Cisco Systems Inc. and Palo Alto Networks Inc.
Competitive benchmarking and strategic market concentration
Our research shows high consolidation among traditional defense primes like Lockheed Martin Corporation and RTX Corporation partnering with pure-play cybersecurity specialists to deliver comprehensive protection across hardware, software, and managed security service tiers.
Executive summary of the Defense Cyber Security Market
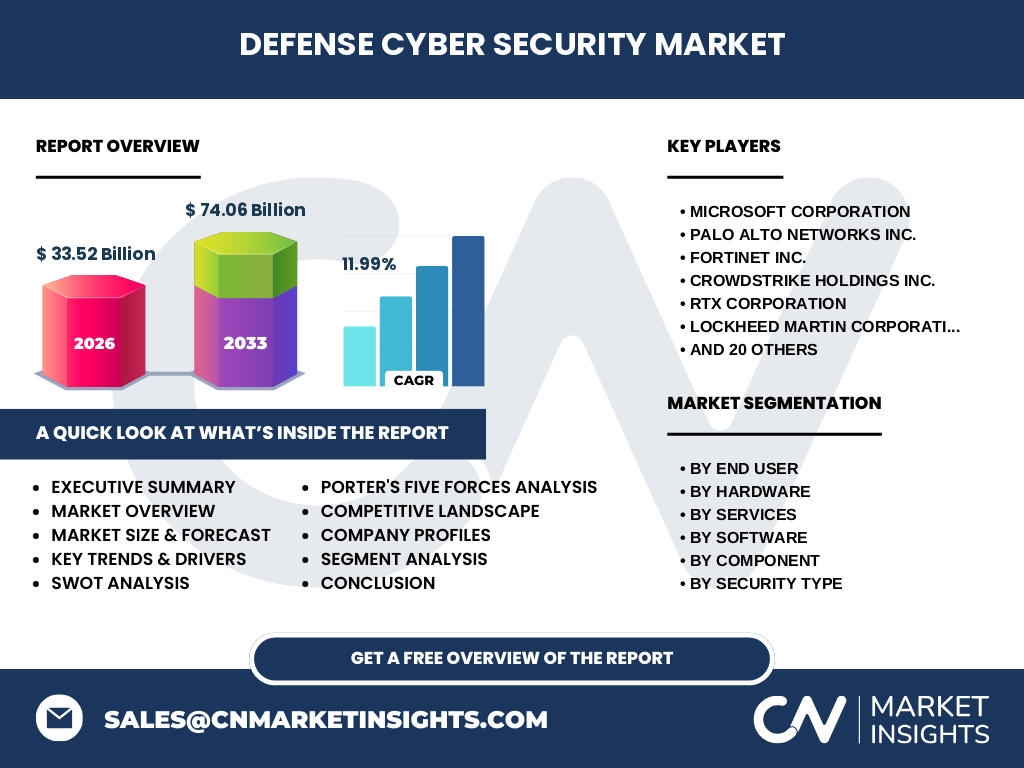
The Defense Cyber Security Market size is valued at 33.52 Billion in 2026, and our forecast projects explosive expansion to 74.06 Billion by 2033, expanding at a robust 11.99% CAGR driven by escalating geopolitical tensions and digital warfare evolution.
Market forecast trajectory from 2027 to 2033
Projected growth from 2027 to 2033 reflects sustained double-digit expansion, scaling the market from its 2026 baseline of 33.52 Billion toward the 74.06 Billion milestone at an 11.99% CAGR, fueled by rising defense budgets worldwide.
Segmentation analysis across hardware, software, and services
The market divides into component categories including Hardware (firewalls, encryptors), Software (SIEM, IAM, EDR), and Services (MSSPs, incident response), alongside deployments via On-Premises and Cloud models serving military and intelligence agencies.
Regional market analysis and geographic distribution
Geographic performance highlights North America as the dominant revenue generator due to heavy Pentagon spending, followed by surging adoption in Europe driven by regional defense modernization mandates and strict cross-border data sovereignty regulations.
In-depth regional review of defense cyber posture
North America anchors baseline demand via major defense integrators, whereas the Asia-Pacific region exhibits the fastest acceleration in Defense Cyber Security Market industry trends, driven by active territorial disputes and aggressive national cybersecurity investments in critical infrastructure.
Company profiles and strategic positioning of key market players
Prominent innovators such as Microsoft Corporation, Thales Group, BAE Systems plc, and Northrop Grumman Corporation leverage advanced threat intelligence and proprietary AI platforms to secure mission-critical military communications against multifaceted cyber incursions.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers remains moderate due to strict government procurement protocols, while threat of new entrants is low given high security clearances, stringent certification requirements, and the massive R&D investments required by established players like General Dynamics Corporation.
SWOT analysis of the defense cybersecurity ecosystem
Key strengths lie in advanced encryption and threat intelligence capabilities, offset by weaknesses in legacy military hardware integration. Opportunities thrive in cloud-native defense architectures, while threats persist from sophisticated zero-day exploits deployed by adversarial nation-states.
Value chain analysis from raw materials to end-users
The value chain flows from semiconductor silicon sourcing and secure component fabrication through software algorithm development by firms like Zscaler Inc. and Trellix, ultimately delivering integrated protection solutions to military and intelligence end-users.
Investment insights and high-potential growth pockets
Strategic recommendations highlight endpoint detection and response software, cloud security overlays, and automated incident response services as high-potential areas offering superior return on investment for venture capitalists and defense contractors alike.
Conclusion and key strategic takeaways
Achieving an 11.99% CAGR to reach 74.06 Billion by 2033 underscores that robust cyber defense is no longer optional; market participants must prioritize agile software solutions and managed services to capture expanding government defense budgets.
Research methodology for baseline triangulation
Our analysis triangulates baseline estimates by combining primary stakeholder interviews with defense CIOs, exhaustive trade registry data, and secondary macroeconomic indicators to ensure absolute accuracy in our Defense Cyber Security Market analysis.
Scope of the report and coverage parameters
This report covers global deployment models, hardware appliances, software solutions, and security services across military, government, and intelligence sectors from 2026 to 2033, acknowledging limitations inherent in classified military expenditure data across certain allied nations.
Recent developments and strategic industry movements
Recent strategic moves feature high-profile acquisitions and partnership expansions among firms like Leidos Holdings Inc., Booz Allen Hamilton Holding Corporation, and CACI International Inc, aimed at bolstering automated threat intelligence for coalition forces.